I don’t think most people wake up one morning and decide, “Today I’m going to get myself deeply into debt.”
It usually happens differently.
We want something, or convince ourselves we need it, and someone shows us a monthly payment we can afford.
That’s where the trouble begins.
I recently experienced this twice.
The first was buying a new living room set. I knew what I wanted, negotiated the price, and prepared to pay cash. The salesperson suggested financing for 18 months because it was “interest free.” When I pointed out it was deferred interest, she insisted it was interest free, so I asked her for the application so I could review the terms.
When the paperwork printed, there it was: 39% interest, along with a monthly payment.
If the balance wasn’t fully paid by the end of the promotional period, the accumulated interest would be charged retroactively. Of course, that important detail was never mentioned.
The statement made it easy to think, “I’m making my required payments, and this will be paid off within the promotional period.” I had to do the math myself to figure out what I actually needed to pay each month to avoid the deferred interest.
That’s the trap: the person who doesn’t understand how deferred interest works can follow the statement, make every minimum payment on time, and still end up owing thousands in accumulated interest when the promotional period ends.
When I pointed out that this was deferred-interest financing and that the minimum payment shown was nowhere near what was required to pay off the balance within 18 months, she claimed the terms were between me and the credit company; she was just selling furniture.
And this brings me back to the point I made at the beginning. I walked into the store ready to pay cash, but the salesperson had an incentive to convince me to finance instead. The problem is that once a buyer accepts the financing, the focus shifts to the monthly payment rather than the actual cost of the purchase. And when the person selling the financing doesn’t clearly explain the terms, an uneducated buyer can easily fall into the trap.
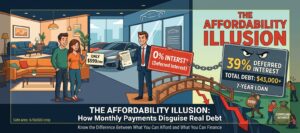
A monthly payment isn’t the price of something; it’s just the way the real cost is being presented to you.
The exact same dynamic played out when I bought a car.
My son had just gotten his driver’s license, so we needed another vehicle. I decided to buy a car for my wife, drive the minivan myself, and give my older 4Runner to my son.
I researched, negotiated, and intended to pay cash.
In the finance office, the pitch started. Before we even got to financing, the finance manager tried selling me an extended warranty, VIN etching on the windows, and other add-ons. I pointed out that none of these were necessary and that they were adding considerably to the overall cost of the car. Despite his pitch about why I needed them, I wasn’t interested.
His response? Why pay cash when I could finance the car, invest my money, and potentially make more than I would pay in interest? Suddenly, he was playing financial advisor.
Out of curiosity, I asked him what the interest rate would be and what my monthly payment would look like. He never gave me the interest rate. Instead, he quoted a monthly payment without even telling me the loan term.
When I pointed out that the payment was too high, he came back with a much lower one. Of course, there was a catch. The loan term had gone from three years to six.
The car wasn’t cheaper. The interest hadn’t disappeared. He had simply stretched out the payments.
I pointed out that this kind of deal could leave me owing more on the car than it was worth, even after years of making payments. His response? He wasn’t offering financial advice; he just sold cars.
But he had already offered financial advice when he encouraged me to finance the car and invest my cash.
I stopped him, picked up my checkbook, and paid cash.
Both experiences left me frustrated.
Yes, consumers must take responsibility, read the contract, calculate the total cost, and know the difference between a want and a need.
But sales systems are explicitly designed around human psychology.
A $600 monthly payment sounds manageable.
$43,000 plus interest sounds daunting.
The payment gets stretched, warranties get rolled in, and the customer feels like the problem is solved.
It isn’t. The obligation hasn’t disappeared. It’s simply been stretched out.
What happens when the system rewards the person closing the sale, while the long-term financial fallout belongs entirely to the customer?
The lesson is simple: don’t confuse manageable costs with sound economics.
For me, financial freedom is knowing the difference between what I can afford and what I can finance. It’s understanding that a monthly payment isn’t the price of an item. It’s just how the price is being presented to me.
Sami Joueidi holds a Master’s degree in Electrical Engineering and brings over 15 years of experience leading AI-driven transformations across startups and enterprises. A seasoned technology leader, Sami has led customer adoption programs, cross-functional engineering teams, and go-to-market strategies that deliver real business impact.
He’s passionate about turning complex ideas into practical solutions, and about helping teams bridge the gap between innovation and execution. Whether architecting scalable systems or demystifying AI concepts, Sami brings a blend of strategic thinking and hands-on problem-solving to every challenge. © Sami Joueidi and www.cafesami.com, 2025. Feel free to share excerpts with proper credit and a link back to the original post.